Protect Your Household, Leave a Legacy
“Love your family enough to prepare for the day you can no longer provide for them yourself.”
From paycheck protection and mortgage payoff to cancer defense and emergency accident cash, Nancy Samantha Aguilar helps you choose the exact shield your family needs.
Freedom of Choice™ Final Expense Certificate
When loss occurs, families are thrust into mourning while facing urgent funeral bills. Funeral homes commonly demand full payment before any arrangements begin. The Freedom of Choice™ certificate solves this heartbreak completely.
Official Funeral Benefit Plan
AIL Home Office: 1-800-433-3405
Protect Your Household. Provide for Their Future. Leave a Legacy.
Protect your household, provide for their future. Leave behind a legacy, not a liability, so your loved ones can focus on healing and honoring life rather than scrambling for emergency funds.
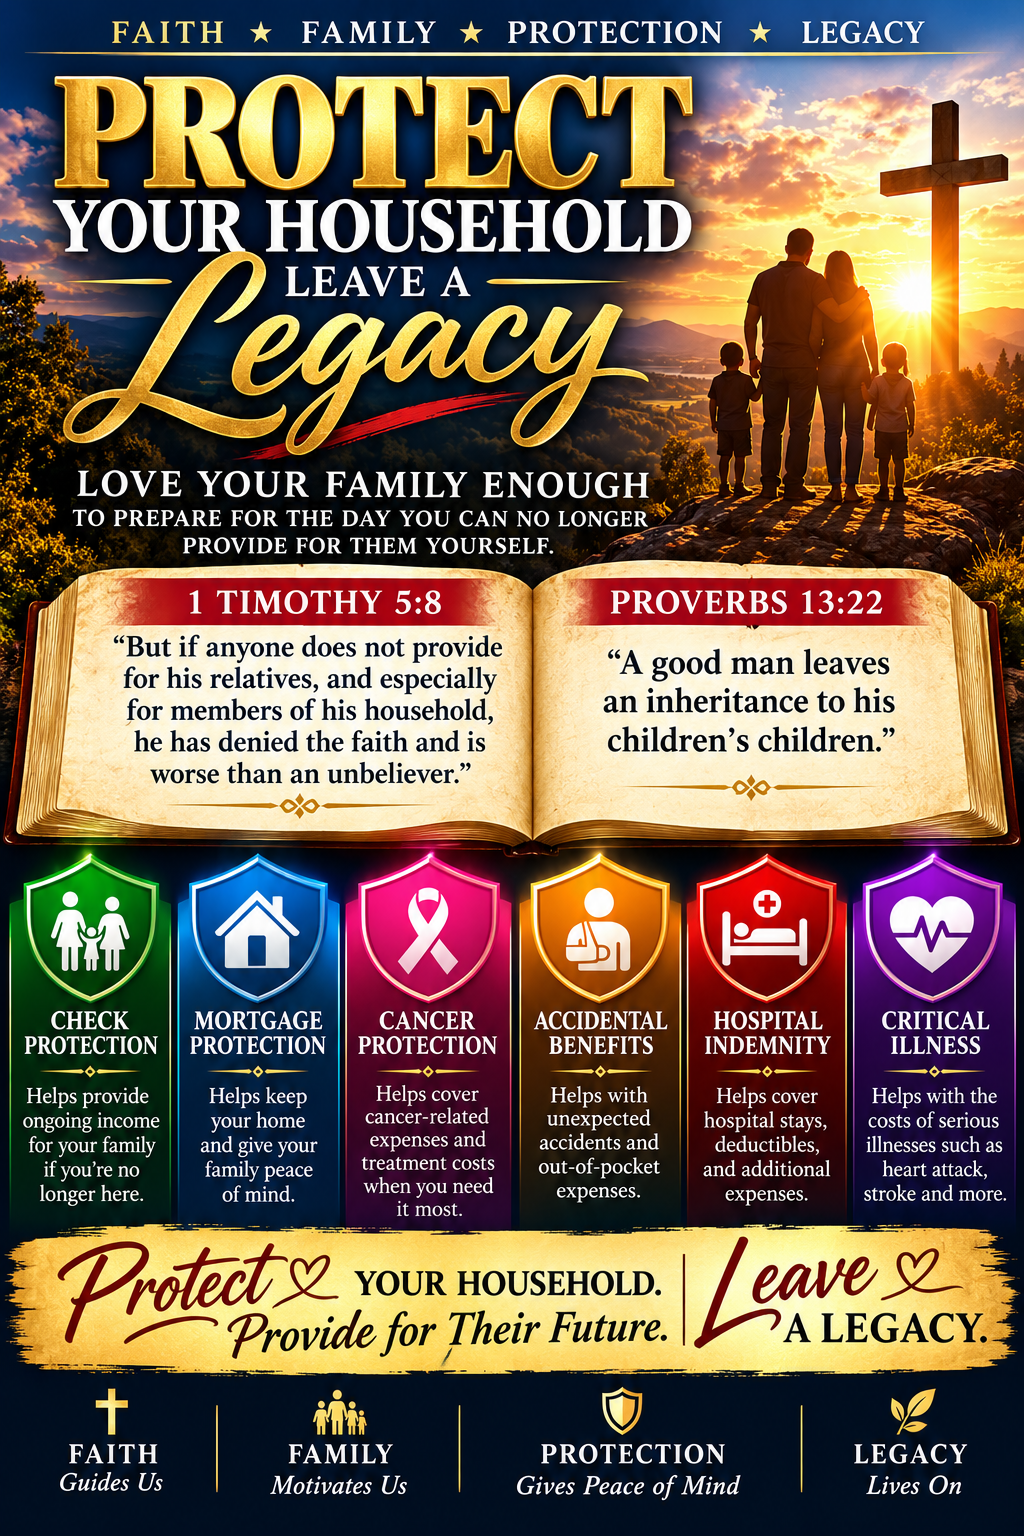
Official AO Household Protection Guide
Presented by Nancy Samantha Aguilar
Six Specialized Household Protections
Every household is vulnerable to different life events. Nancy works with you to select the exact combination of coverage that buffers your family's income, home, and savings.
Check Protection
Income Continuation
“Helps provide ongoing income for your family if you're no longer here.”
Replaces the vital paycheck your household depends on each month so your family can maintain their standard of living, pay regular bills, buy groceries, and cover utilities without immediate financial distress.
Mortgage Protection
Keep Your Home
“Helps keep your home and give your family peace of mind.”
Ensures your spouse and children never lose the roof over their heads. Designed to cover the mortgage balance or provide monthly mortgage payments if you pass away, become disabled, or face critical illness.
Cancer Protection
First Diagnosis & Treatment
“Choose a lump-sum cancer payout or a cancer fund that pays the cancer bills regardless of other insurance.”
A cancer diagnosis brings staggering indirect expenses — experimental treatments, specialty co-pays, travel to cancer centers, and lost wages. Two plan structures are available: a lump-sum cancer payout (issued in $10,000, $25,000, or $50,000 benefit tiers) paid directly to you on a positive pathology diagnosis, or a Cancer Fund Protection plan that pays all of your cancer bills regardless of other insurance, with benefit limits from $25,000 up to $150,000 for single or family coverage. Availability varies by state — some states are excluded, so Nancy confirms eligibility for your ZIP code first.
Accidental Benefits
Unexpected Emergency Care
“Helps with unexpected accidents and out-of-pocket expenses.”
Accidents happen without warning. This coverage provides immediate cash assistance for emergency room visits, fractures, dislocations, burns, accidental disability, and accidental death.
Hospital Indemnity
Inpatient & Deductible Buffer
“Helps cover hospital stays, deductibles, and additional expenses.”
High-deductible health plans and surprise hospital stays can drain savings fast. Hospital Indemnity pays fixed cash amounts directly to you for every day admitted to a hospital or ICU.
Critical Illness
Major Medical Event Defense
“Helps with the costs of serious illnesses such as heart attack, stroke, and more.”
Surviving a major illness like a heart attack, stroke, major organ failure, or paralysis often requires months of rehabilitation. Provides a lump sum of tax-free cash upon diagnosis to keep your life moving forward.
The Right Coverage for Your Stage of Life
Product availability is set by age. Seniors 60 and up qualify for a focused set of guaranteed-issue protections, while applicants 59 and under have access to the complete household suite. Nancy matches you to exactly what your age and family need.
Age 60 & Up — Senior Coverage
Guaranteed-Issue Senior Set
Seniors 60 and older qualify for a focused set of guaranteed-issue protections: Cancer Protection, Accidental Benefits, and Life Insurance & Final Expense.
Age 59 & Under — Full Household Suite
Complete Household Suite
Applicants 59 and under have access to the complete household protection suite — including income continuation, mortgage payoff, and critical illness defense.
Whole Life & Term Insurance Options
Beyond the household protection suite, applicants age 59 and under can choose from a complete menu of permanent whole life and non-smoker term products — each matched to your budget, obligations, and legacy goals.
Whole Life & Permanent Coverage
Permanent whole life products with guaranteed level premiums, guaranteed cash value growth, and a death benefit that never expires. Premiums never increase with age or health changes.
Life Paid-Up at 65
Last chance to qualify by age 50
Whole life coverage where premiums stop at age 65 — the policy becomes fully paid-up with no further payments due, yet protection continues for the rest of your life. The last opportunity to qualify is age 50.
Premium Life
Enhanced cash value whole life
Premium whole life protection with enhanced cash value accumulation and a guaranteed lifetime death benefit — permanent protection plus living benefits you can access.
Executive Life
Higher-coverage whole life
Executive-level whole life designed for higher coverage needs, with accelerated cash value growth and flexible premium payment options for professionals and growing families.
Select Life Coverage
Guaranteed whole life
Select whole life coverage offering guaranteed level premiums and a guaranteed death benefit for life — straightforward, permanent protection that cannot be cancelled for health reasons.
Term Insurance — Non-Smoker Rates
Affordable term protection with preferred non-smoker rates. Choose the term length that matches your obligations — and convert to permanent coverage anytime without re-qualifying.
20-Year Term Insurance
Level term · Non-smoker
Level-premium term coverage locked in for 20 full years with preferred non-smoker rates. Your premium and death benefit stay fixed for the entire term.
4-Year Renewable Convertible
Short-term · Non-smoker
Short-term renewable convertible term with non-smoker rates. Renew annually as needed and convert to permanent whole life coverage at any time — no medical re-qualification required.
Term Insurance to Age 65
Working-years term · Non-smoker
Term protection that stays in force until age 65 with preferred non-smoker rates — covering your highest-earning, highest-obligation years when your family needs protection most.
30-Year Decreasing Term
Decreasing benefit · Non-smoker
30-year decreasing term with non-smoker rates — the death benefit reduces over time as your mortgage and debts are paid down, keeping premiums low while your largest obligations shrink.
15-Year Decreasing Term
Decreasing benefit · Non-smoker
15-year decreasing term with non-smoker rates — protection that scales down over 15 years as loans and obligations are paid off, at a lower cost than level term insurance.
10-Year Renewable Convertible
10-year term · Non-smoker
10-year renewable convertible term with preferred non-smoker rates. Renew at the end of each term or convert to permanent whole life coverage whenever you are ready — no medical exam required.
Waiver of Premium Disability Rider
If you become totally disabled, the company takes over your premiums — your coverage stays in force and your family stays protected, even when you can no longer earn.
The Waiver of Premium rider is an optional add-on available on eligible whole life and term policies. If the insured becomes totally disabled (as defined by the policy) for the waiting period specified in the contract, the insurance company waives all future premium payments and assumes them itself. Your policy remains fully in force — cash value keeps growing, the death benefit stays intact, and your family's protection is never interrupted by a disability that takes away your income.
Disability Protection
Add the Waiver of Premium rider to keep your coverage in force if a disability ever takes away your ability to pay.
Children's Coverage — Head Start Program
Give your children a lifetime of protection from day one — a $10,000 Freedom of Choice child rider for just $6.25 a month, or start them on their own permanent Head Start policy they can grow into for life.
Freedom of Choice Child Rider
Added to your existing policy
Add $10,000 of Freedom of Choice final expense coverage for your child directly onto your own policy for just $6.25 a month. That flat rate covers every child in your household — whether you have 1 child or 10 — with the same guaranteed acceptance and universal funeral-home honoring as the adult certificate.
One flat rate — $6.25 a month covers all your children, whether you have 1 child or 10.
Head Start Program — Give Your Children a Head Start on Their Future!
Give your children the gift of lifelong protection and future insurability.
The Head Start Program is designed to help parents and grandparents secure life insurance protection for their children today, while giving them the opportunity to increase their coverage as they grow into adulthood and start families of their own.
Here's How It Works
Coverage Increase Opportunities
| Age | Total Potential Coverage |
|---|---|
| Childhood | $25,000 |
| 25 | $50,000 |
| 28 | $75,000 |
| 31 | $100,000 |
| 34 | $125,000 |
| 37 | $150,000 |
| 40 | $175,000 |
Protect Their Future Before They Need It
You can't predict your child's future health, but you can help protect their ability to obtain additional life insurance coverage.
Give them a Head Start today, so they're better prepared to protect their own family tomorrow.
Coverage increases are optional, require additional premiums, and are subject to the policy's guaranteed insurability provisions, eligibility requirements, and applicable terms. Availability and benefits may vary by state and policy.
Terminal Illness Rider
Every plan includes a terminal illness rider at no extra cost. If you're diagnosed with a terminal illness and deemed to have less than 12 months to live, your death benefit is accelerated — half paid to you while you're still here, and half paid to your family after you pass.
When a terminal diagnosis comes, the last thing your family should worry about is money. The Terminal Illness rider is built into every AO Globe Life plan at no additional premium. Upon certification by a physician that you have a terminal illness with a life expectancy of less than 12 months, your death benefit is accelerated — up to half is paid to you while you're still living to help with care, comfort, and final arrangements, and the remaining half is paid to your beneficiaries after you pass.
Accelerated death benefit — half paid to you for care and comfort, half to your family after.
Cancer Protection — Plan Options & State Availability
Cancer Protection comes in two structures. A lump-sum payout pays you directly on a positive pathology diagnosis in a $10,000, $25,000, or $50,000 benefit tier. A Cancer Fund Protection plan pays all of your cancer bills regardless of any other insurance you carry, with benefit limits from $25,000 up to $150,000 for single or family coverage. Availability varies by state — some states are excluded — so Nancy confirms your state's eligibility before enrollment.
Cancer Protection availability varies by state. Some states are excluded entirely. Nancy verifies your state and ZIP code before any enrollment.
Lump-Sum Cancer Payout
Paid directly to you on diagnosis
A one-time cash benefit issued upon a positive pathology diagnosis. You choose the benefit tier — the funds are yours to spend on treatment, travel, lost wages, or however your family needs them.
Cancer Fund Protection
Pays all cancer bills regardless of other insurance
Instead of a single lump sum, the Cancer Fund pays your actual cancer bills as they come due — regardless of any other insurance you carry. Benefit limits run from $25,000 – $150,000 with single or family coverage.
Not sure which cancer structure fits your family? Nancy walks through both options, confirms your state's availability, and shows exactly what each pays — at no cost.
Why Cancer Protection Matters
Cancer Risk
Historically, approximately 1 in 2 men and 1 in 3 women develop cancer during their lifetime. Current estimates vary.
Financial Impact
Cancer treatment can create serious financial hardship, with some patients facing $20,000 or more in annual out-of-pocket expenses.
230+ Types of Cancer
Most cancers cannot be identified through inherited genetic testing or routine bloodwork.
Insurance Gaps
Health insurance does not always cover every treatment, medication, travel expense, or loss of income. Some treatments may not be FDA-approved.
Lack of Awareness
Many Americans are unaware that supplemental cancer protection is available.
Health insurance helps cover medical treatment. Cancer protection can help safeguard your family's finances.
Life Insurance & Final Expense
Permanent whole life protection with guaranteed cash values, level premiums that never increase, and immediate death benefits that don't get tied up in probate.
Will & Legacy Planning Kit
Comprehensive planning resources including medical power of attorney guidance, vital document organizers, and final wish declarations for your family.
The Family Stays in Control — Not the Funeral Director
Walk a civilian policy worth $65,000 into a funeral home and watch what happens to the invoice. Freedom of Choice™ eliminates the markup game entirely: the beneficiary assigns the amount the funeral home is allowed to collect, and every dollar left over comes back to the family tax-free within a day or two.
The $65,000 Walk-In Scenario
A side-by-side of what actually happens at the funeral home
$65,000
$65,000
When the policy is made payable to the funeral home, the entire death benefit is on the table — and the invoice tends to climb to match it.
$65,000
Only the actual funeral cost
The beneficiary decides how much the funeral home is allowed to draw. That assigned amount is all the director has to work with.
The entire remainder
Whatever is left after the real funeral bill is paid comes back to the beneficiary within a day or two — not absorbed into the invoice.
The Civilian Policy Problem
A traditional life insurance policy made payable to the funeral home hands the director the full death benefit — and the incentive to charge it all. There is an entire 60 Minutes investigation into how often grieving families are taken advantage of this way. The funeral home sees the payout, inflates the invoice, and the family never sees the difference.
The Freedom of Choice™ Solution
Freedom of Choice™ flips the power back to the family. The beneficiary — not the funeral director — assigns the exact amount the funeral home is permitted to collect. The director verifies that amount instantly through the Attention Funeral Director hotline, bills only that, and hands the certificate back. The remaining balance returns to the beneficiary tax-free within a day or two to handle every other expense. The family goes home to grieve in peace with no financial burden hanging over their heads.
“Hand the funeral director the certificate, set the amount, and go home. Grieve in peace — not in panic. The money stays with the family, where it belongs.”
Trust vs. Will
Know the difference — and why Nancy sets up a will for every client
Nancy sets up a will for every client she meets with. Understanding the difference between a Will and a Trust is one of the most important parts of protecting your family's legacy. The short version: a will controls what happens after you die, while a trust can control assets during life and after death — and usually avoids probate.
Important Clarification
Advanced Directives (Living Will & Healthcare Proxy) are for MEDICAL WISHES ONLY — not estate planning. They do not control your assets. A Will or Trust is what handles your estate.
What a Will Does
Controls assets after death
A will is a legal document that controls what happens to your assets after death.
What a Trust Does
Controls assets during life & after death
A (revocable living) trust is a legal entity that holds your assets — during life and after death.
Side-by-Side Comparison
| Feature | Will | Trust |
|---|---|---|
| When it takes effect | After death | During life and after death |
| Probate required | Yes | No (if funded properly) |
| Privacy | Public record | Private |
| Speed for heirs | Slower (months to a year+) | Faster (often weeks) |
| Upfront cost | Lower | Higher |
| Names guardians for kids | Yes | No (you still need a will for this) |
Most Complete Estate Plans Use Both
The strongest estate plans pair a trust with a pour-over will:
Holds and distributes your assets — avoiding probate and keeping things private.
Catches anything left outside the trust and names guardians for minor children.
Opening a trust is basically a three-part process: create it, sign it, and fund it. Here's the full breakdown:
Decide on the type of trust
Most people open a revocable living trust because it lets them stay in control while alive and helps avoid probate later.
Choose the key people
You will name:
Create the trust document
An estate attorney or online legal service prepares the trust agreement. This is the legal document that controls everything.
Sign and notarize the trust
You sign the document in front of a notary. At this point, the trust officially exists.
Fund the trust (most important step)
You must move assets into the trust's name. This may include:
Tell your successor trustee where documents are
Make sure they know the trust exists and where to find it when needed.
“Let’s think about this for a moment.”
A personal note from Nancy
Most people only seriously think about life insurance at one of three moments:
And chances are, you may not have this conversation again for another 10, 20, or even 30 years. By then, you’ll be older, coverage could cost significantly more, and your health may have changed.
With all due respect, neither of us is getting any younger. Ideally, we would have taken care of this 25 years ago, but we can’t change yesterday. What we can do is take care of your family today.
This is one of those decisions that can make a tremendous difference when your family needs it most.
So let’s get the protection you qualify for in place, at a payment you’re comfortable with, and give your family one less thing to worry about.
Because the best time to prepare for tomorrow is while we still have today.
Unsure Which Plan Best Fits Your Family?
Nancy provides zero-cost, pressure-free policy audits. We can examine your current policies, explain beneficiary rules, and identify duplicate or costly gaps.